Convertible bonds provide a hybrid solution for investors looking for a balanced exposure to financial markets that combines the attractive elements of both equities and bonds. They aim to deliver upside participation in rising markets while helping protect capital during downturns.
Emerging & Frontier Markets strategies focus on capturing high-growth opportunities across the world’s fastest-growing economies. With a long-standing, index-agnostic approach, the team invests both directly in these markets and in developed market companies with significant exposure to them.
By harnessing the power of dividends, our team aims to deliver a combination of income and long-term capital growth by investing in a diversified portfolio of global equities. The strategy is designed for investors seeking a disciplined approach, targeting a rare combination of premium yield, durable income, and attractive valuation, while selectively investing in overlooked opportunities where short-term controversies have created potential mispricing
Redwheel’s Global Intrinsic Value team is led by Ian Lance and Nick Purves, who each have over 30 years’ investment experience and have worked together for nearly 20 years across multiple market cycles. Alongside a team of global analysts, they are dedicated value investors seeking to identify undervalued, durable companies with strong cash flows and robust balance sheets.
Structural shifts driven by regulation, technological innovation, and the global energy transition are creating long-term growth opportunities across infrastructure sectors. Our team invests in publicly traded companies across developed and emerging markets that provide essential services and assets supporting economic activity and societal development.
Our Natural Capital strategy seeks to deliver long-term capital growth by investing in global companies that contribute to the preservation and restoration of the planet’s natural resources. As ecosystems come under increasing pressure from pollution and resource depletion, while remaining fundamental to economic and societal stability, we see a compelling opportunity in nature-positive solutions.
Our Active Ownership strategies are built on the belief that companies with active, engaged shareholders are more likely to generate superior long-term returns. The core focus of the strategies is to invest in concentrated portfolios of European and Japanese companies that are receptive to engagement, targeting fundamentally sound businesses with significant upside potential over a three- to five-year time horizon.
At Redwheel, Stewardship is our overarching approach to responsible investing, bringing together Sustainability, Active Ownership and Greenwheel Research & Insights into a single, disciplined framework. Through this framework we integrate material sustainability considerations into investment decisions, support investment teams with central expertise, and use focused engagement, proxy voting and thematic research to protect and enhance long-term client outcomes.
Against a backdrop of high interest rates and heightened uncertainty, we examine whether recent market volatility has created an attractive investment opportunity in the electricity sector. In environments where growth is accelerating, and valuations appear to be approaching trough levels, history suggests that the electricity sector has the potential to perform well once interest rates peak.
The market generally regards utilities and renewables as interest rate sensitive sectors, given their long-duration cash flows and relatively high gearing. As a result, when long bond yields peak, as is the case this year, the sector has come under pressure irrespective of company fundamentals. We have therefore seen broad weakness in the US utility index, down 14.4% [1] since early June, while the renewables and clean energy sector has also been falling, with the S&P Global Clean Energy Transition Index down 29% over the same period[1].
Against this backdrop, we examined whether the market has been mistaken and the reaction excessive. We analysed the correlation of the Redwheel Global Renewables Infrastructure Strategy (GRI) with interest rates, over 5-10 years. The correlation ranged from -0.4 to -0.3, indicating only a moderate negative correlation [2].
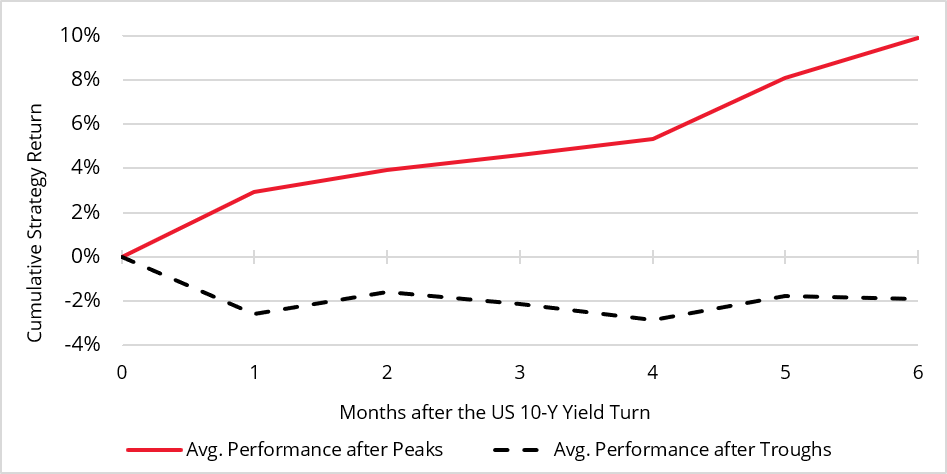
In addition, we sought to understand how the Strategy performed when interest rates peaked and troughed since inception [2]. In the chart below, we show average performance six months after an identified peak or trough event between December 2015 and August 2026. From the interest rate peaks, the Strategy generated an average return of 10% in the subsequent six months. For example, in October 2023 the Strategy rose 10.4% six months after the US 10-year Treasury yield peaked at 4.99% (and rose 26.9% 12 months after the peak). Interestingly, the skew appears positive for the Strategy: following interest rate troughs over the same period, it declined by less than 2% on average after six months.
Chart 1: Redwheel GRI – Performance after US 10-y Treasury yield peaks and troughs
This analysis suggests that, historically, peaking interest rates have offered attractive entry points for investors. That would be enough of a signal on its own, but the dislocation caused by interest rates comes at a time when fundamentals are strong.
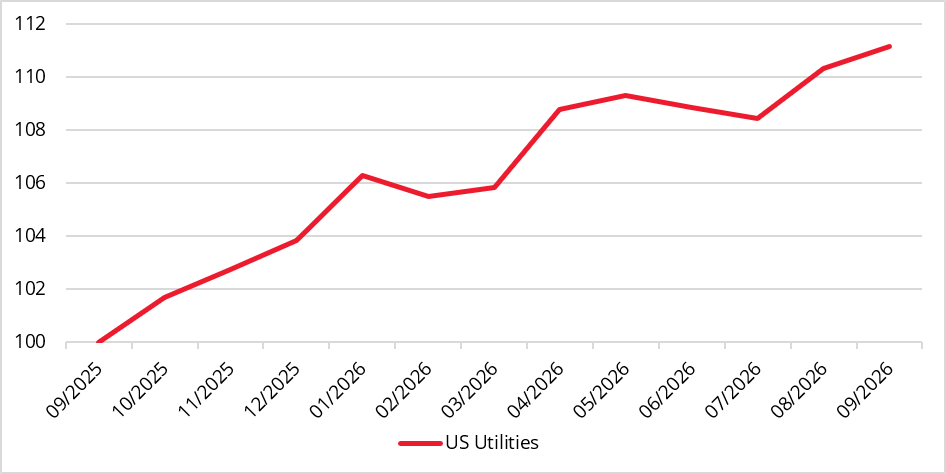
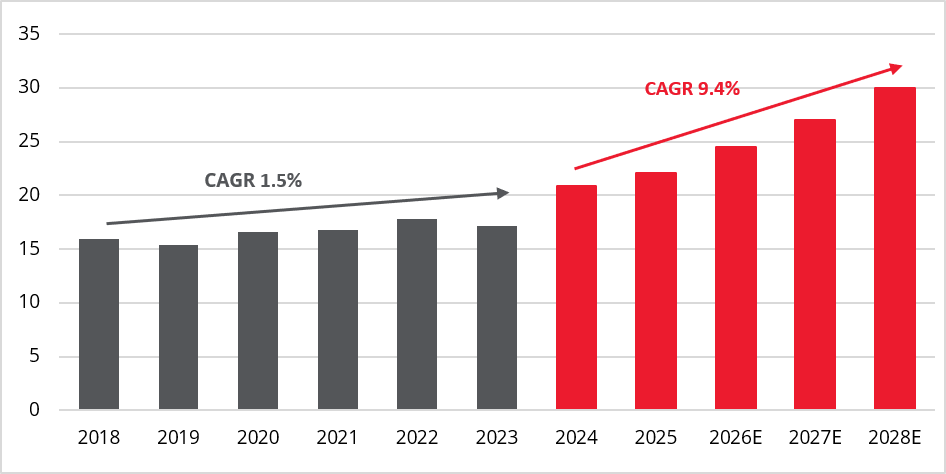
As shown in the charts below, US earnings revisions have been positive in the past 12 months and have accelerated since June, supported by strong first-half results and improved outlooks. Positive earnings revisions feed an already accelerating earnings growth picture for the sector.
Chart 2: US Utilities – Earnings revisions for the last 12 months
Chart 3: US Utilities – Earnings per share from 2018 (USD)
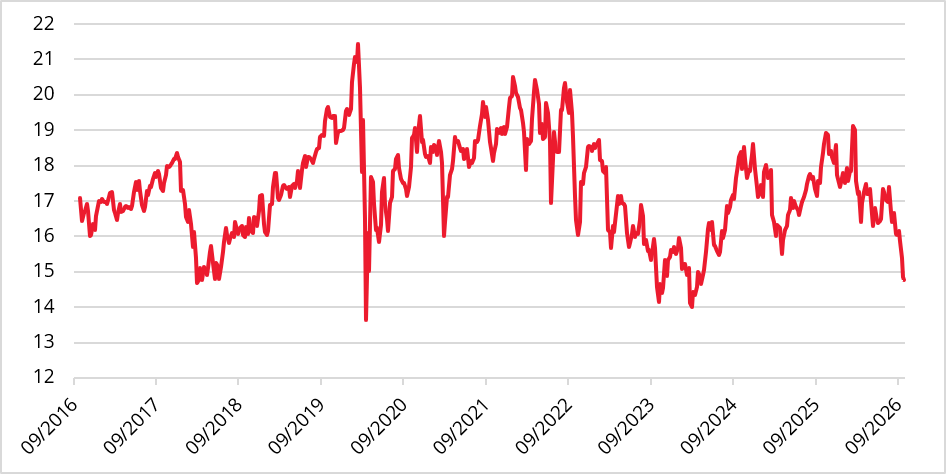
Anecdotally, the chairman of Iberdrola recently indicated that the company could possibly grow earnings by at least 10% per year through 2030 [3]. Nextera [4] has stated it expects to grow earnings by at least 9% per year through 2035. These comments suggest that the two largest companies in the sector globally anticipate growing faster for longer. We would expect that to translate into premium valuations but the market disagrees: as earnings have accelerated and share prices weakened, valuations have compressed near 10-year lows, which has historically been a strong signal for investors.
Chart 4: US Utilities – 1-Year forward PE
We believe the current weakness is an attractive opportunity for investors looking to gain or increase exposure to the sector, particularly in light of past M&A activity that has taken place in similar periods of weakness.
Prepare for M&A
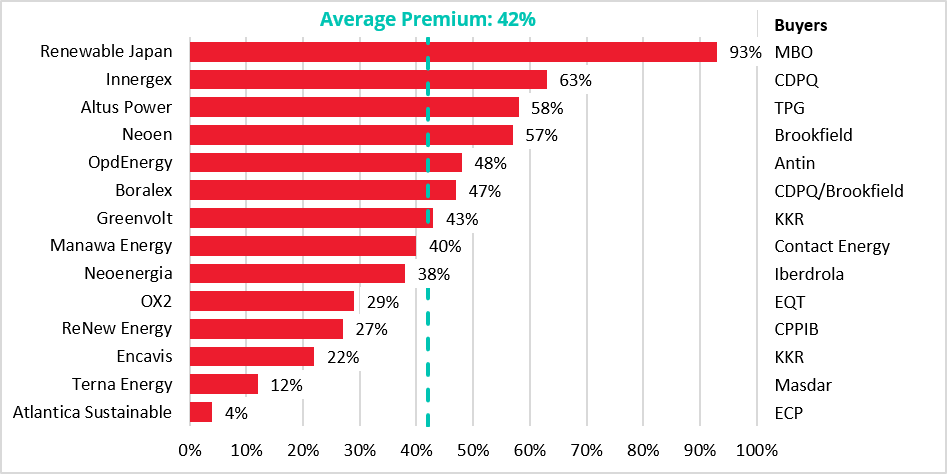
In the absence of a rebound in stock prices, M&A activity could increase, as it did during the sector’s previous down cycle in 2023-2024. As private equity investors tend to have longer-term horizons and can refinance at lower rates over their holding period, they look at short-term dislocations as great buying opportunities. Across the sample presented below, the average acquisition premium was 42% [5].
Chart 5: Recent Take Private Activity: Premium over share price 3 months prior to the offer
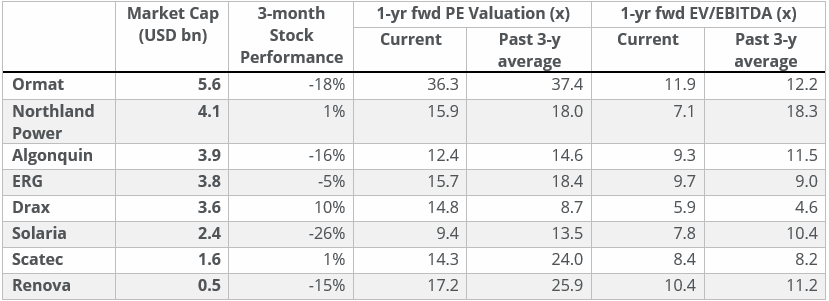
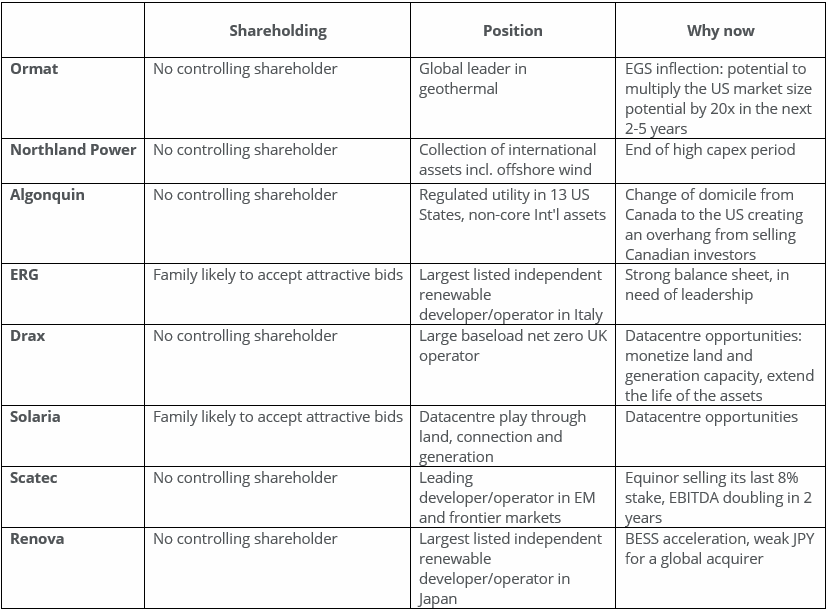
In our investment universe, we have identified the following companies [6] as potential acquisition targets. The selection reflects not only their valuations but also the fact that they are at a strategic or operational inflection point that Private Equity might better appreciate than a stock market gripped by short-term uncertainties and high interest rates.
Table 1: Potential acquisition targets (Financials):
Table 2: Potential acquisition targets (Redwheel analysis):
Key Risk
The principal risk to this thesis is that interest rates continue to rise. If the US 10-year Treasury yield moves towards 5.5%, 6.0% or higher, the sector could experience further valuation pressure and another leg down.
Conclusion
We believe that this is an opportune time for investors to look for entry points in the sector. Historical analysis suggests that periods around peaking interest rates have in the past preceded attractive performance, although we cannot guarantee that this would be the case in the future. However, sector fundamentals are supportive, the earnings trajectory is positive, and valuations are near historical lows despite a stronger growth outlook.
Sources
[1] Bloomberg, September 2026
[2] Redwheel, September 2026
[3] BTIG Investment Bank August Utilities, Renewables, Infrastructure and Energy daily commentary
[4] NextEra website: https://www.investor.nexteraenergy.com/news-and-events/news-releases/2026/05-18-2026-123054903
[5] Bloomberg and Company Announcements
[6] Bloomberg and Redwheel, September 2026
Key Information
No investment strategy or risk management technique can guarantee returns or eliminate risks in any market environment. Past performance is not a guide to the future. The prices of investments and income from them may fall as well as rise and investors may not get back the full amount invested. Forecasts and estimates are based upon subjective assumptions about circumstances and events that may not yet have taken place and may never do so. Portfolio holdings are subject to change without notice. The statements and opinions expressed in this article are those of the author as of the date of publication, and do not necessarily represent the view of Redwheel. This article does not constitute investment advice and the information shown is for illustrative purposes only.
Balanced convertibles are once again delivering meaningful equity participation while outpacing investment grade credit. Davide Basile, Portfolio Manager, Redwheel Convertible Bonds, argues that convertibles have reached a turning point, read more in his latest insight.
Two holdings in the Redwheel Global Equity Income strategy have agreed to be acquired this year, while a third has attracted takeover speculation – rare for a strategy invested in large, liquid companies. Nick Clay, Portfolio Manager, considers what this may reveal about the opportunity in durable businesses overlooked by a market fixated on a single theme.
Despite persistent outflows, global investor underweights and little direct exposure to the AI-led market rally, UK equities have generated strong relative returns. Larry Furness, Redwheel Value & Income, examines how low valuations, share buybacks, takeover activity and the recovery in value stocks have contributed to that outcome.
Redwheel ® and Ecofin ® are registered trademarks of RWC Partners Limited (“RWC”). The term “Redwheel” may include any one or more Redwheel branded regulated entities including RWC Asset Management LLP, which is authorised and regulated by the UK Financial Conduct Authority and the US Securities and Exchange Commission (“SEC”); RWC Asset Advisors (US) LLC, which is registered with the SEC; RWC Singapore (Pte) Limited, which is licensed as a Licensed Fund Management Company by the Monetary Authority of Singapore; Redwheel Australia Pty Ltd is an Australian Financial Services Licensee with the Australian Securities and Investment Commission; and Redwheel Europe Fondsmæglerselskab A/S which is regulated by the Danish Financial Supervisory Authority.
Redwheel may act as investment manager or adviser, or otherwise provide services, to more than one product pursuing a similar investment strategy or focus to the product detailed in this document. Redwheel and RWC (together “Redwheel Group”) seeks to minimise any conflicts of interest, and endeavours to act at all times in accordance with its legal and regulatory obligations as well as its own policies and codes of conduct.
This document is directed only at professional, institutional, wholesale or qualified investors. The services provided by Redwheel are available only to such persons. It is not intended for distribution to and should not be relied on by any person who would qualify as a retail or individual investor in any jurisdiction or for distribution to, or use by, any person or entity in any jurisdiction where such distribution or use would be contrary to local law or regulation.
This document has been prepared for general information purposes only and has not been delivered for registration in any jurisdiction nor has its content been reviewed or approved by any regulatory authority in any jurisdiction.
The information contained herein does not constitute: (i) a binding legal agreement; (ii) legal, regulatory, tax, accounting or other advice; (iii) an offer, recommendation or solicitation to buy or sell shares in any fund, security, commodity, financial instrument or derivative linked to, or otherwise included in a portfolio managed or advised by Redwheel; or (iv) an offer to enter into any other transaction whatsoever (each a “Transaction”). Redwheel Group bears no responsibility for your investment research and/or investment decisions and you should consult your own lawyer, accountant, tax adviser or other professional adviser before entering into any Transaction. No representations and/or warranties are made that the information contained herein is either up to date and/or accurate and is not intended to be used or relied upon by any counterparty, investor or any other third party.
Redwheel Group uses information from third party vendors, such as statistical and other data, that it believes to be reliable. However, the accuracy of this data, which may be used to calculate results or otherwise compile data that finds its way over time into Redwheel Group research data stored on its systems, is not guaranteed. If such information is not accurate, some of the conclusions reached or statements made may be adversely affected. Any opinion expressed herein, which may be subjective in nature, may not be shared by all directors, officers, employees, or representatives of Group and may be subject to change without notice. Redwheel Group is not liable for any decisions made or actions or inactions taken by you or others based on the contents of this document and neither Redwheel Group nor any of its directors, officers, employees, or representatives (including affiliates) accepts any liability whatsoever for any errors and/or omissions or for any direct, indirect, special, incidental, or consequential loss, damages, or expenses of any kind howsoever arising from the use of, or reliance on, any information contained herein.
Information contained in this document should not be viewed as indicative of future results. Past performance of any Transaction is not indicative of future results. The value of investments can go down as well as up. Certain assumptions and forward looking statements may have been made either for modelling purposes, to simplify the presentation and/or calculation of any projections or estimates contained herein and Redwheel Group does not represent that that any such assumptions or statements will reflect actual future events or that all assumptions have been considered or stated. There can be no assurance that estimated returns or projections will be realised or that actual returns or performance results will not materially differ from those estimated herein. Some of the information contained in this document may be aggregated data of Transactions executed by Redwheel that has been compiled so as not to identify the underlying Transactions of any particular customer.
No representations or warranties of any kind are intended or should be inferred with respect to the economic return from, or the tax consequences of, an investment in a Redwheel-managed fund.
This document expresses no views as to the suitability or appropriateness of the fund or any other investments described herein to the individual circumstances of any recipient.
The information transmitted is intended only for the person or entity to which it has been given and may contain confidential and/or privileged material. In accepting receipt of the information transmitted you agree that you and/or your affiliates, partners, directors, officers and employees, as applicable, will keep all information strictly confidential. Any review, retransmission, dissemination or other use of, or taking of any action in reliance upon, this information is prohibited. Any distribution or reproduction of this document is not authorised and is prohibited without the express written consent of Redwheel Group.
Funds managed by Redwheel are not, and will not be, registered under the Securities Act of 1933 (the “Securities Act”) and are not available for purchase by US persons (as defined in Regulation S under the Securities Act) except to persons who are “qualified purchasers” (as defined in the Investment Company Act of 1940) and “accredited investors” (as defined in Rule 501(a) under the Securities Act).
This document does not constitute an offer to sell, purchase, subscribe for or otherwise invest in units or shares of any fund managed by Redwheel. Any offering is made only pursuant to the relevant offering document and the relevant subscription application. Prospective investors should review the offering memorandum in its entirety, including the risk factors in the offering memorandum, before making a decision to invest.
AIFMD and Distribution in the European Economic Area (“EEA”)
The Alternative Fund Managers Directive (Directive 2011/61/EU) (“AIFMD”) is a regulatory regime which came into full effect in the EEA on 22 July 2014. RWC Asset Management LLP is an Alternative Investment Fund Manager (an “AIFM”) to certain funds managed by it (each an “AIF”). The AIFM is required to make available to investors certain prescribed information prior to their investment in an AIF. The majority of the prescribed information is contained in the latest Offering Document of the AIF. The remainder of the prescribed information is contained in the relevant AIF’s annual report and accounts. All of the information is provided in accordance with the AIFMD.
In relation to each member state of the EEA (each a “Member State”), this document may only be distributed and shares in a Redwheel fund (“Shares”) may only be offered and placed to the extent that (a) the relevant Redwheel fund is permitted to be marketed to professional investors in accordance with the AIFMD (as implemented into the local law/regulation of the relevant Member State); or (b) this document may otherwise be lawfully distributed and the Shares may lawfully be offered or placed in that Member State (including at the initiative of the investor).
Information Required for Offering in Switzerland of Foreign Collective Investment Schemes to Qualified Investors within the meaning of Article 10 CISA.
This is an advertising document.
The representative and paying agent of the Redwheel-managed funds in Switzerland (the “Representative in Switzerland”) FIRST INDEPENDENT FUND SERVICES LTD, Feldeggstrasse 12, CH-8008 Zurich. Swiss Paying Agent: Helvetische Bank AG, Seefeldstrasse 215, CH-8008 Zurich. In respect of the units of the Redwheel-managed funds offered in Switzerland, the place of performance is at the registered office of the Swiss Representative. The place of jurisdiction is at the registered office of the Swiss Representative or at the registered office or place of residence of the investor.
No investment strategy or risk management technique can guarantee returns or eliminate risks in any market environment.The term “RWC” may include any one or more RWC branded entities including RWC Partners Limited and RWC Asset Management LLP, each of which is authorised and regulated by the UK Financial Conduct Authority and, in the case of RWC Asset Management LLP, the US Securities and Exchange Commission; RWC Asset Advisors (US) LLC, which is registered with the US Securities and Exchange Commission; and RWC Singapore (Pte) Limited, which is licensed as a Licensed Fund Management Company by the Monetary Authority of Singapore.RWC may act as investment manager or adviser, or otherwise provide services, to more than one product pursuing a similar investment strategy or focus to the product detailed in this audio. RWC seeks to minimise any conflicts of interest, and endeavours to act at all times in accordance with its legal and regulatory obligations as well as its own policies and codes of conduct.This audio is directed only at professional, institutional, wholesale or qualified investors. The services provided by RWC are available only to such persons. It is not intended for distribution to and should not be relied on by any person who would qualify as a retail or individual investor in any jurisdiction or for distribution to, or use by, any person or entity in any jurisdiction where such distribution or use would be contrary to local law or regulation.This audio has been prepared for general information purposes only and has not been delivered for registration in any jurisdiction nor has its content been reviewed or approved by any regulatory authority in any jurisdiction. The information contained herein does not constitute: (i) a binding legal agreement; (ii) legal, regulatory, tax, accounting or other advice; (iii) an offer, recommendation or solicitation to buy or sell shares in any fund, security, commodity, financial instrument or derivative linked to, or otherwise included in a portfolio managed or advised by RWC; or(iv) an offer to enter into any other transaction whatsoever (each a “Transaction”). No representations and/or warranties are made that the information contained herein is either up to date and/or accurate and is not intended to be used or relied upon by any counterparty, investor or any other third party.RWC uses information from third party vendors, such as statistical and other data, that it believes to be reliable. However, the accuracy of this data, which may be used to calculate results or otherwise compile data that finds its way over time into RWC research data stored on its systems, is not guaranteed. If such information is not accurate, some of the conclusions reached or statements made may be adversely affected. RWC bears no responsibility for your investment research and/or investment decisions and you should consult your own lawyer, accountant, tax adviser or other professional adviser before entering into any Transaction. Any opinion expressed herein, which may be subjective in nature, may not be shared by all directors, officers, employees, or representatives of RWC and may be subject to change without notice. RWC is not liable for any decisions made or actions or in actions taken by you or others based on the contents of this audio and neither RWC nor any of its directors, officers, employees, or representatives (including affiliates) accepts any liability whatsoever for any errors and/or omissions or for any direct, indirect, special, incidental, or consequential loss, damages, or expenses of any kind howsoever arising from the use of, or reliance on, any information contained herein.Information contained in this audio should not be viewed as indicative of future results. Past performance of any Transaction is not indicative of future results. The value of investments can go down as well as up. Certain assumptions and forward looking statements may have been made either for modelling purposes, to simplify the audio and/or calculation of any projections or estimates contained herein and RWC does not represent that that any such assumptions or statements will reflect actual future events or that all assumptions have been considered or stated. Forward-looking statements are inherently uncertain, and changing factors such as those affecting the markets generally, or those affecting particular industries or issuers, may cause results to differ from those discussed. Accordingly, there can be no assurance that estimated returns or projections will be realised or that actual returns or performance results will not materially differ from those estimated herein. Some of the information contained in this audio may be aggregated data of Transactions executed by RWC that has been compiled so as not to identify the underlying Transactions of any particular customer.The information transmitted is intended only for the person or entity to which it has been given and may contain confidential and/or privileged material. In accepting receipt of the information transmitted you agree that you and/or your affiliates, partners, directors, officers and employees, as applicable, will keep all information strictly confidential. Any review, retransmission, dissemination or other use of, or taking of any action in reliance upon, this information is prohibited. The information contained herein is confidential and is intended for the exclusive use of the intended recipient(s) to which this audio has been provided. Any distribution or reproduction of this audio is not authorised and is prohibited without the express written consent of RWC or any of its affiliates.Changes in rates of exchange may cause the value of such investments to fluctuate. An investor may not be able to get back the amount invested and the loss on realisation may be very high and could result in a substantial or complete loss of the investment. In addition, an investor who realises their investment in a RWC-managed fund after a short period may not realise the amount originally invested as a result of charges made on the issue and/or redemption of such investment. The value of such interests for the purposes of purchases may differ from their value for the purpose of redemptions. No representations or warranties of any kind are intended or should be inferred with respect to the economic return from, or the tax consequences of, an investment in a RWC-managed fund. Current tax levels and reliefs may change. Depending on individual circumstances, this may affect investment returns. Nothing in this document constitutes advice on the merits of buying or selling a particular investment. This audio expresses no views as to the suitability or appropriateness of the fund or any other investments described herein to the individual circumstances of any recipient.AIFMD and Distribution in the European Economic Area (“EEA”)The Alternative Fund Managers Directive (Directive 2011/61/EU)(“AIFMD”) is a regulatory regime which came into full effect in the EEA on 22 July 2014. RWC Asset Management LLP is an Alternative Investment Fund Manager (an “AIFM”) to certain funds managed by it (each an “AIF”). The AIFM is required to make available to investors certain prescribed information prior to their investment in an AIF. The majority of the prescribed information is contained in the latest Offering Document of the AIF. The remainder of the prescribed information is contained in the relevant AIF’s annual report and accounts. All of the information is provided in accordance with the AIFMD.In relation to each member state of the EEA (each a “Member State”),this document may only be distributed and shares in a RWC fund(“Shares”) may only be offered and placed to the extent that (a) the relevant RWC fund is permitted to be marketed to professional investors in accordance with the AIFMD (as implemented into the local law/regulation of the relevant Member State); or (b) this audio may otherwise be lawfully distributed and the Shares may lawfully offered or placed in that Member State (including at the initiative of the investor).Information Required for Distribution of Foreign Collective Investment Schemes to Qualified Investors in SwitzerlandThe representative and paying agent of the RWC-managed funds in Switzerland (the “Representative in Switzerland”) FIRST INDEPENDENT FUND SERVICES LTD, Klausstrasse 33, CH-8008 Zurich. Swiss Paying Agent: Helvetische Bank AG, Seefeldstrasse 215, CH-8008 Zurich. In respect of the units of the RWC-managed funds distributed in Switzerland, the place of performance and jurisdiction is at the registered office of the Representative in Switzerland.