Convertibles deserve a fresh look

For much of the past decade, investors could reasonably overlook convertible bonds. Equity markets rose strongly, traditional fixed income offered little income, and the hybrid characteristics of the asset class could appear less compelling than a straightforward allocation to either stocks or bonds.

However, many of those headwinds have reversed. Markets today face a less settled mix of growth, inflation, policy and geopolitical risks, heralding a higher volatility backdrop. A significant new issuance calendar with better structures and sectorial dynamics is widening the available opportunity set.

In this environment, we believe convertibles merit renewed attention, and the recent performance of the asset class indicates this as we notice a much higher participation to the equity upside combined with a better capital preservation backdrop.

Chart 1: Balanced global convertibles vs global equities and investment grade bonds – Total return
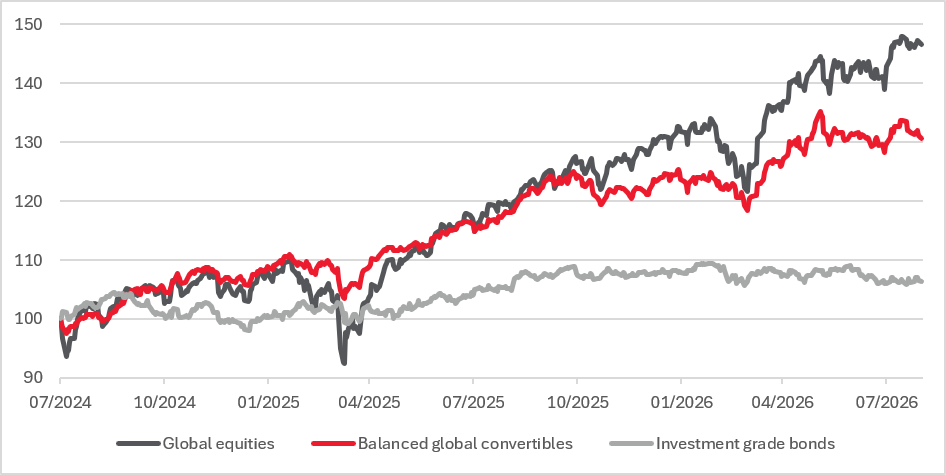
Source: Bloomberg, 31 July 2026. Normalised to 100. FTSE Global Focus Convertible Hedge Index USD, iShares iBoxx USD Investment Grade Corporate Bond ETF and MSCI World index. Past performance is not a guide to future results.
A more supportive income backdrop

The higher-rate environment has changed the composition of the convertible market. During the era of exceptionally low interest rates, many new issues were structured with minimal coupons and were valued primarily for their equity optionality. More recently, the income component of the asset class has become more meaningful, particularly among balanced convertibles.

That matters because the bond element can provide carry and, subject to issuer creditworthiness, a degree of support when equity markets weaken. At the same time, the embedded option preserves the potential to participate in equity upside. This combination can create a more balanced risk and return profile than an allocation consisting solely of equities or conventional bonds, particularly when considering some of the compelling growth dynamics of some of the issuers.

Convexity has become more relevant

The investment case for convertibles is closely linked to convexity. A balanced convertible bond can participate as the issuer’s share price rises, while its bond characteristics may become more relevant when the share price falls. In simple terms, the objective is not to eliminate losses, but to seek a more favourable balance between upside participation and downside resilience.

This feature can be particularly valuable in a market environment marked by abrupt changes in sentiment. Policy announcements, geopolitical developments, fiscal concerns and elevated equity valuations have all contributed to periods of sharp cross-asset repricing. We would not characterise this as proof of a permanently higher-volatility regime. However, compared with the unusually calm conditions that prevailed for parts of the previous decade, markets appear more vulnerable to episodic shocks.

This increased volatility is generally beneficial for the asset class, from both the increasing value of the convertible but also where a portfolio holds genuinely balanced issues and is actively managed, changing equity sensitivity can create opportunities to rebalance exposure as markets move.

A larger and more diverse primary market

Supply is an important part of the current opportunity. A healthy primary market does more than increase the headline size of the asset class: it refreshes the universe, introduces new issuers and sectors, and gives investors more choice across credit quality, maturity, coupon and equity sensitivity.

Recent issuance has been supported by companies seeking to finance investment, refinance existing debt and preserve flexibility in their capital structures. For issuers, convertibles can lower immediate cash-interest costs relative to straight debt while limiting dilution relative to an immediate equity raise. For investors, new deals can offer access to structures and businesses that may not otherwise be available in the secondary market.

Chart 2 and 3: Convertible issuance (USD bn)
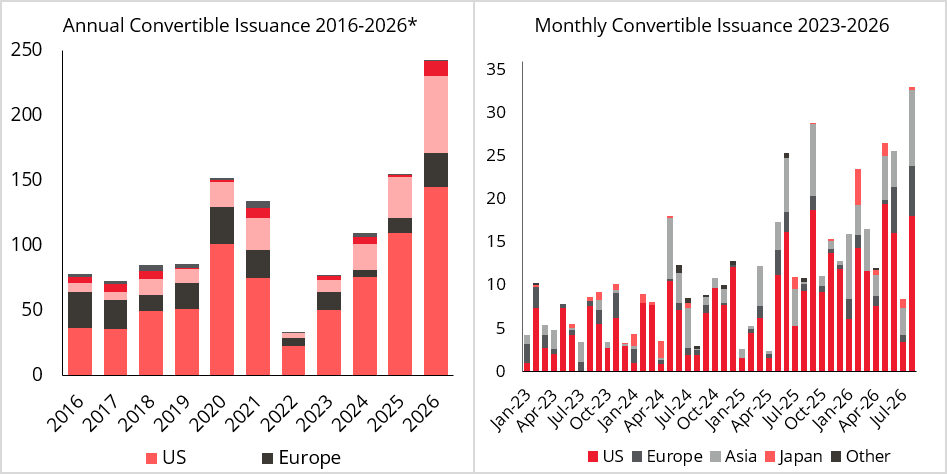
*Figure for 2026 is annualised. Source: Redwheel, FTSE, Bloomberg, Reuters, UBS data as at 31 July 2026. The information shown above is for illustrative purposes only.
Accessing growth themes with a different risk profile

The expansion of artificial intelligence, cloud infrastructure, data centres and related technology investment is also influencing convertible issuance. Growth-oriented businesses often have substantial funding needs and may favour a convertible structure that combines debt financing with future equity participation.

For investors, this can create a way to gain exposure to long-term growth themes without making a wholly equity-like allocation. Recent issuance from AI-cloud and data-centre-related companies illustrates the role convertibles can play in financing the infrastructure behind these themes. These can offer great ways to access the potential long-term benefits of AI while mitigating the downside given the valuations that some companies may be experiencing could be considered too high particularly if the growth were not to materialise in the expected timeframe.

Beyond a narrow equity market

A further reason to revisit convertibles is their potential role in reducing reliance on a small number of dominant equity-market names. Global equity returns have been heavily influenced by a concentrated group of mega-cap companies. While those businesses remain important, a portfolio tied too closely to a narrow leadership group can become more exposed to valuation risk and changes in market breadth.

The convertible universe provides access to a wider range of companies, including mid-cap growth businesses across technology, healthcare, industrials, consumer and other sectors. This does not mean convertibles will necessarily outperform in every market. A prolonged rally led by the largest equities can favour a conventional equity index. But if leadership broadens, a diversified convertible portfolio may offer exposure to areas of the market that are less well represented in mega-cap benchmarks.

A distinct role in asset allocation

Convertibles should not be regarded merely as a mechanical blend of equities and bonds. Their behaviour changes with the underlying share price, interest rates, credit spreads, volatility and the individual terms of each security. That can make them a useful source of diversification, but it also means they need a clear role within a portfolio, particularly when volatility is elevated.

For some investors, the asset class may sit alongside equity allocations as a way to seek growth with a potentially more balanced profile. For others, it may complement fixed income by adding equity optionality. A dedicated allocation can also be appropriate where investors want to assess the hybrid opportunity set on its own merits.

The right position will depend on an investor’s objectives, risk tolerance, liquidity needs and governance framework. What is increasingly difficult to argue, in our view, is that convertibles can be assessed solely through an equity or bond lens.

A timely moment to reassess

In conclusion, we feel the turning point has been realised after a long period of muted performance. Balanced convertibles are once again delivering meaningful equity participation while outpacing investment grade credit, and providing enhanced reward characteristics driven by several aspects including:

– More meaningful Income component

– Return of Volatility and the value of convexity in an episodic market backdrop

– Broadening equity leadership and the opportunity to diversify concentrated equity exposure

– Expanding primary market

– Risk-managed exposure to secular high-growth themes

Based on this we feel balanced convertibles are once again a relevant and powerful tool for today’s asset allocation challenges.


Key Information

No investment strategy or risk management technique can guarantee returns or eliminate risks in any market environment. Past performance is not a guide to the future. The prices of investments and income from them may fall as well as rise and investors may not get back the full amount invested. Forecasts and estimates are based upon subjective assumptions about circumstances and events that may not yet have taken place and may never do so. The statements and opinions expressed in this article are those of the author as of the date of publication, and do not necessarily represent the view of Redwheel. This article does not constitute investment advice and the information shown is for illustrative purposes only.
In case you missed it

Global Equity Income

Two holdings in the Redwheel Global Equity Income strategy have agreed to be acquired this year, while a third has attracted takeover speculation – rare for a strategy invested in large, liquid companies. Nick Clay, Portfolio Manager, considers what this may reveal about the opportunity in durable businesses overlooked by a market fixated on a single theme.

21 September, 2026 | 03:38pm
Global Intrinsic Value

Despite persistent outflows, global investor underweights and little direct exposure to the AI-led market rally, UK equities have generated strong relative returns. Larry Furness, Redwheel Value & Income, examines how low valuations, share buybacks, takeover activity and the recovery in value stocks have contributed to that outcome.

16 September, 2026 | 09:35am
Convertible Bonds

Davide Basile, Lead Portfolio Manager, Redwheel Convertible Bonds, marks the first year of Redwheel’s Enhanced Index Focus Convertibles strategy. He explores the case for balanced global convertible exposure and explains how the Strategy’s three implementation levers seek to offset fees and enhance net returns.

9 September, 2026 | 03:10pm

Disclaimer

Redwheel ® and Ecofin ® are registered trademarks of RWC Partners Limited (“RWC”). The term “Redwheel” may include any one or more Redwheel branded regulated entities including RWC Asset Management LLP, which is authorised and regulated by the UK Financial Conduct Authority and the US Securities and Exchange Commission (“SEC”); RWC Asset Advisors (US) LLC, which is registered with the SEC;  RWC Singapore (Pte) Limited, which is licensed as a Licensed Fund Management Company by the Monetary Authority of Singapore; Redwheel Australia Pty Ltd is an Australian Financial Services Licensee with the Australian Securities and Investment Commission; and Redwheel Europe Fondsmæglerselskab A/S which is regulated by the Danish Financial Supervisory Authority.

Redwheel may act as investment manager or adviser, or otherwise provide services, to more than one product pursuing a similar investment strategy or focus to the product detailed in this document. Redwheel and RWC (together “Redwheel Group”) seeks to minimise any conflicts of interest, and endeavours to act at all times in accordance with its legal and regulatory obligations as well as its own policies and codes of conduct.

This document is directed only at professional, institutional, wholesale or qualified investors. The services provided by Redwheel are available only to such persons. It is not intended for distribution to and should not be relied on by any person who would qualify as a retail or individual investor in any jurisdiction or for distribution to, or use by, any person or entity in any jurisdiction where such distribution or use would be contrary to local law or regulation.

This document has been prepared for general information purposes only and has not been delivered for registration in any jurisdiction nor has its content been reviewed or approved by any regulatory authority in any jurisdiction.

The information contained herein does not constitute: (i) a binding legal agreement; (ii) legal, regulatory, tax, accounting or other advice; (iii) an offer, recommendation or solicitation to buy or sell shares in any fund, security, commodity, financial instrument or derivative linked to, or otherwise included in a portfolio managed or advised by Redwheel; or (iv) an offer to enter into any other transaction whatsoever (each a “Transaction”). Redwheel Group bears no responsibility for your investment research and/or investment decisions and you should consult your own lawyer, accountant, tax adviser or other professional adviser before entering into any Transaction. No representations and/or warranties are made that the information contained herein is either up to date and/or accurate and is not intended to be used or relied upon by any counterparty, investor or any other third party.

Redwheel Group uses information from third party vendors, such as statistical and other data, that it believes to be reliable. However, the accuracy of this data, which may be used to calculate results or otherwise compile data that finds its way over time into Redwheel Group research data stored on its systems, is not guaranteed. If such information is not accurate, some of the conclusions reached or statements made may be adversely affected. Any opinion expressed herein, which may be subjective in nature, may not be shared by all directors, officers, employees, or representatives of Group and may be subject to change without notice. Redwheel Group is not liable for any decisions made or actions or inactions taken by you or others based on the contents of this document and neither Redwheel Group nor any of its directors, officers, employees, or representatives (including affiliates) accepts any liability whatsoever for any errors and/or omissions or for any direct, indirect, special, incidental, or consequential loss, damages, or expenses of any kind howsoever arising from the use of, or reliance on, any information contained herein.

Information contained in this document should not be viewed as indicative of future results. Past performance of any Transaction is not indicative of future results. The value of investments can go down as well as up. Certain assumptions and forward looking statements may have been made either for modelling purposes, to simplify the presentation and/or calculation of any projections or estimates contained herein and Redwheel Group does not represent that that any such assumptions or statements will reflect actual future events or that all assumptions have been considered or stated. There can be no assurance that estimated returns or projections will be realised or that actual returns or performance results will not materially differ from those estimated herein. Some of the information contained in this document may be aggregated data of Transactions executed by Redwheel that has been compiled so as not to identify the underlying Transactions of any particular customer.

No representations or warranties of any kind are intended or should be inferred with respect to the economic return from, or the tax consequences of, an investment in a Redwheel-managed fund.

This document expresses no views as to the suitability or appropriateness of the fund or any other investments described herein to the individual circumstances of any recipient.

The information transmitted is intended only for the person or entity to which it has been given and may contain confidential and/or privileged material. In accepting receipt of the information transmitted you agree that you and/or your affiliates, partners, directors, officers and employees, as applicable, will keep all information strictly confidential. Any review, retransmission, dissemination or other use of, or taking of any action in reliance upon, this information is prohibited. Any distribution or reproduction of this document is not authorised and is prohibited without the express written consent of Redwheel Group.

Funds managed by Redwheel are not, and will not be, registered under the Securities Act of 1933 (the “Securities Act”) and are not available for purchase by US persons (as defined in Regulation S under the Securities Act) except to persons who are “qualified purchasers” (as defined in the Investment Company Act of 1940) and “accredited investors” (as defined in Rule 501(a) under the Securities Act).

This document does not constitute an offer to sell, purchase, subscribe for or otherwise invest in units or shares of any fund managed by Redwheel. Any offering is made only pursuant to the relevant offering document and the relevant subscription application. Prospective investors should review the offering memorandum in its entirety, including the risk factors in the offering memorandum, before making a decision to invest.

AIFMD and Distribution in the European Economic Area (“EEA”)

The Alternative Fund Managers Directive (Directive 2011/61/EU) (“AIFMD”) is a regulatory regime which came into full effect in the EEA on 22 July 2014. RWC Asset Management LLP is an Alternative Investment Fund Manager (an “AIFM”) to certain funds managed by it (each an “AIF”). The AIFM is required to make available to investors certain prescribed information prior to their investment in an AIF. The majority of the prescribed information is contained in the latest Offering Document of the AIF. The remainder of the prescribed information is contained in the relevant AIF’s annual report and accounts. All of the information is provided in accordance with the AIFMD.

In relation to each member state of the EEA (each a “Member State”), this document may only be distributed and shares in a Redwheel fund (“Shares”) may only be offered and placed to the extent that (a) the relevant Redwheel fund is permitted to be marketed to professional investors in accordance with the AIFMD (as implemented into the local law/regulation of the relevant Member State); or (b) this document may otherwise be lawfully distributed and the Shares may lawfully be offered or placed in that Member State (including at the initiative of the investor).

Information Required for Offering in Switzerland of Foreign Collective Investment Schemes to Qualified Investors within the meaning of Article 10 CISA.

This is an advertising document.

The representative and paying agent of the Redwheel-managed funds in Switzerland (the “Representative in Switzerland”) FIRST INDEPENDENT FUND SERVICES LTD, Feldeggstrasse 12, CH-8008 Zurich. Swiss Paying Agent: Helvetische Bank AG, Seefeldstrasse 215, CH-8008 Zurich. In respect of the units of the Redwheel-managed funds offered in Switzerland, the place of performance is at the registered office of the Swiss Representative. The place of jurisdiction is at the registered office of the Swiss Representative or at the registered office or place of residence of the investor.

No investment strategy or risk management technique can guarantee returns or eliminate risks in any market environment.The term “RWC” may include any one or more RWC branded entities including RWC Partners Limited and RWC Asset Management LLP, each of which is authorised and regulated by the UK Financial Conduct Authority and, in the case of RWC Asset Management LLP, the US Securities and Exchange Commission; RWC Asset Advisors (US) LLC, which is registered with the US Securities and Exchange Commission; and RWC Singapore (Pte) Limited, which is licensed as a Licensed Fund Management Company by the Monetary Authority of Singapore.RWC may act as investment manager or adviser, or otherwise provide services, to more than one product pursuing a similar investment strategy or focus to the product detailed in this audio. RWC seeks to minimise any conflicts of interest, and endeavours to act at all times in accordance with its legal and regulatory obligations as well as its own policies and codes of conduct.This audio is directed only at professional, institutional, wholesale or qualified investors. The services provided by RWC are available only to such persons. It is not intended for distribution to and should not be relied on by any person who would qualify as a retail or individual investor in any jurisdiction or for distribution to, or use by, any person or entity in any jurisdiction where such distribution or use would be contrary to local law or regulation.This audio has been prepared for general information purposes only and has not been delivered for registration in any jurisdiction nor has its content been reviewed or approved by any regulatory authority in any jurisdiction. The information contained herein does not constitute: (i) a binding legal agreement; (ii) legal, regulatory, tax, accounting or other advice; (iii) an offer, recommendation or solicitation to buy or sell shares in any fund, security, commodity, financial instrument or derivative linked to, or otherwise included in a portfolio managed or advised by RWC; or(iv) an offer to enter into any other transaction whatsoever (each a “Transaction”). No representations and/or warranties are made that the information contained herein is either up to date and/or accurate and is not intended to be used or relied upon by any counterparty, investor or any other third party.RWC uses information from third party vendors, such as statistical and other data, that it believes to be reliable. However, the accuracy of this data, which may be used to calculate results or otherwise compile data that finds its way over time into RWC research data stored on its systems, is not guaranteed. If such information is not accurate, some of the conclusions reached or statements made may be adversely affected. RWC bears no responsibility for your investment research and/or investment decisions and you should consult your own lawyer, accountant, tax adviser or other professional adviser before entering into any Transaction. Any opinion expressed herein, which may be subjective in nature, may not be shared by all directors, officers, employees, or representatives of RWC and may be subject to change without notice. RWC is not liable for any decisions made or actions or in actions taken by you or others based on the contents of this audio and neither RWC nor any of its directors, officers, employees, or representatives (including affiliates) accepts any liability whatsoever for any errors and/or omissions or for any direct, indirect, special, incidental, or consequential loss, damages, or expenses of any kind howsoever arising from the use of, or reliance on, any information contained herein.Information contained in this audio should not be viewed as indicative of future results. Past performance of any Transaction is not indicative of future results. The value of investments can go down as well as up. Certain assumptions and forward looking statements may have been made either for modelling purposes, to simplify the audio and/or calculation of any projections or estimates contained herein and RWC does not represent that that any such assumptions or statements will reflect actual future events or that all assumptions have been considered or stated. Forward-looking statements are inherently uncertain, and changing factors such as those affecting the markets generally, or those affecting particular industries or issuers, may cause results to differ from those discussed. Accordingly, there can be no assurance that estimated returns or projections will be realised or that actual returns or performance results will not materially differ from those estimated herein. Some of the information contained in this audio may be aggregated data of Transactions executed by RWC that has been compiled so as not to identify the underlying Transactions of any particular customer.The information transmitted is intended only for the person or entity to which it has been given and may contain confidential and/or privileged material. In accepting receipt of the information transmitted you agree that you and/or your affiliates, partners, directors, officers and employees, as applicable, will keep all information strictly confidential. Any review, retransmission, dissemination or other use of, or taking of any action in reliance upon, this information is prohibited. The information contained herein is confidential and is intended for the exclusive use of the intended recipient(s) to which this audio has been provided. Any distribution or reproduction of this audio is not authorised and is prohibited without the express written consent of RWC or any of its affiliates.Changes in rates of exchange may cause the value of such investments to fluctuate. An investor may not be able to get back the amount invested and the loss on realisation may be very high and could result in a substantial or complete loss of the investment. In addition, an investor who realises their investment in a RWC-managed fund after a short period may not realise the amount originally invested as a result of charges made on the issue and/or redemption of such investment. The value of such interests for the purposes of purchases may differ from their value for the purpose of redemptions. No representations or warranties of any kind are intended or should be inferred with respect to the economic return from, or the tax consequences of, an investment in a RWC-managed fund. Current tax levels and reliefs may change. Depending on individual circumstances, this may affect investment returns. Nothing in this document constitutes advice on the merits of buying or selling a particular investment. This audio expresses no views as to the suitability or appropriateness of the fund or any other investments described herein to the individual circumstances of any recipient.AIFMD and Distribution in the European Economic Area (“EEA”)The Alternative Fund Managers Directive (Directive 2011/61/EU)(“AIFMD”) is a regulatory regime which came into full effect in the EEA on 22 July 2014. RWC Asset Management LLP is an Alternative Investment Fund Manager (an “AIFM”) to certain funds managed by it (each an “AIF”). The AIFM is required to make available to investors certain prescribed information prior to their investment in an AIF. The majority of the prescribed information is contained in the latest Offering Document of the AIF. The remainder of the prescribed information is contained in the relevant AIF’s annual report and accounts. All of the information is provided in accordance with the AIFMD.In relation to each member state of the EEA (each a “Member State”),this document may only be distributed and shares in a RWC fund(“Shares”) may only be offered and placed to the extent that (a) the relevant RWC fund is permitted to be marketed to professional investors in accordance with the AIFMD (as implemented into the local law/regulation of the relevant Member State); or (b) this audio may otherwise be lawfully distributed and the Shares may lawfully offered or placed in that Member State (including at the initiative of the investor).Information Required for Distribution of Foreign Collective Investment Schemes to Qualified Investors in SwitzerlandThe representative and paying agent of the RWC-managed funds in Switzerland (the “Representative in Switzerland”) FIRST INDEPENDENT FUND SERVICES LTD, Klausstrasse 33, CH-8008 Zurich. Swiss Paying Agent: Helvetische Bank AG, Seefeldstrasse 215, CH-8008 Zurich. In respect of the units of the RWC-managed funds distributed in Switzerland, the place of performance and jurisdiction is at the registered office of the Representative in Switzerland.