When unusual events point to unusual times

Unusual events in the Redwheel Global Equity Income Strategy may reveal something about today’s equity market: its fixation on a single, dominant theme, and its certainty about the outcome.

The Strategy invests predominantly in large-cap companies: 94% of the Strategy is allocated to stocks classified as large cap, although our disciplines mean we own none of the world’s ten largest companies[1]. One consequence is that our holdings are rarely takeover targets. More often, they are the companies doing the bidding. Before this year, the last bid for a portfolio holding came in July 2020.

Against that history, the events of 2026 so far are striking. Within a matter of months, two portfolio companies agreed to be acquired and a third is the subject of ongoing takeover speculation. What would normally be exceptional has begun to look like a pattern.

In our view, this is evidence that the Strategy holds some global, best-in-class companies at attractive valuations. It also illustrates how the market’s myopic certainty that AI is the only theme that matters is creating opportunities among durable businesses that fall outside the narrative.

An unusual run of interest on our holdings[2]

Beazley Plc.[3], the specialist insurance company, was bid for by Zurich Insurance Group (another holding in the Strategy) in January this year. The final agreed price of £13.35 per share (cash and dividend) was a premium of 63% to the £8.20 per share price prior to the announcement[4].

In April, Intertek, the global testing company, agreed to be acquired by private equity firm EQT. The offer will give shareholders £61.08 per share (cash and dividend), a premium of 62% to the undisturbed price of £37.70 per share (9 April) prior to the announcement.[5]

Meanwhile, insurer Hiscox’s shares rose sharply in May following press reports that Canada’s Intact Financial was exploring a possible approach, although no offer had been made at the time.[6]

These were not obscure micro-cap businesses. Beazley and Intertek each had an equity market value of roughly £5 billion before the respective approaches. Their size, liquidity and established franchises make the concentration of bid activity within the Strategy all the more unusual.

In our view, this unusual sequence is evidence of something broader: attractive valuations are available across many parts of the market, even among large, high-quality businesses. Strategic and financial buyers appear increasingly willing to act on an opportunity that public markets have been overlooking.

The reason lies partly in the market’s narrow fixation on AI. Confidence about the likely winners – and equal certainty about the presumed losers – has directed capital towards a small group of favoured companies. Away from that theme, many sound businesses now trade on valuations rarely seen in their own histories. Such is the market’s certainty of the future, it is not simply rewarding expected beneficiaries of AI; in some cases, it is pricing potential disruption as though decline were close to inevitable.

When disruption is priced as certain decline

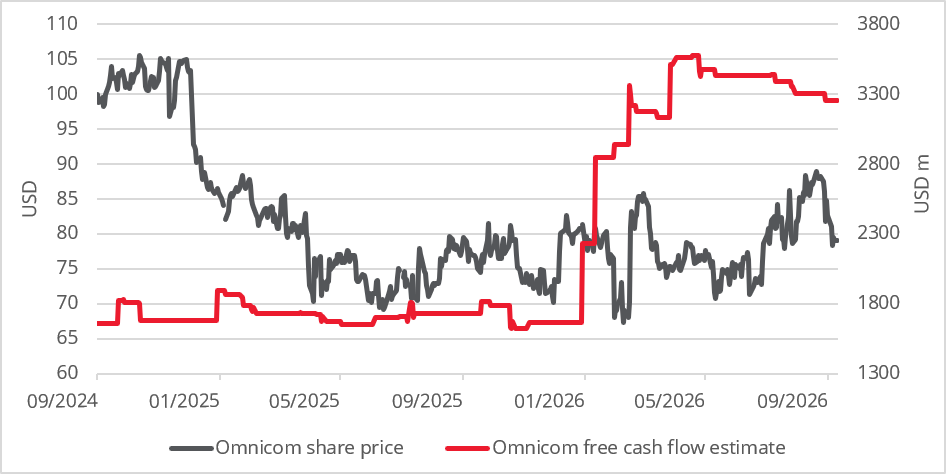
Omnicom Group, the leading global advertiser, is currently valued at a market capitalisation of approximately $24bn[7], with net debt estimated at $3bn at the end of 2026. That valuation represents estimates for the full year 2026 of $26bn of revenue, $3bn net income and $3.4bn of free cashflow. That is around 1x revenue, 8x net income and a free cash flow yield of approximately 14%, while generating a dividend yield of 4.5%. By our analysis, the market is implying that Omnicom could well be bust within seven years.[8]

Chart 1: Omnicom Group – Share price performance since downturn vs free cash flow estimates
Source: Bloomberg, 9 September 2026. Share price, LHS. Free cash flow, RHS, shows Bloomberg point-in-time consensus estimates for FY2026 and FY2027. The information shown above is for illustrative purposes only. Past performance is not a guide to future results.

Of course, nothing can be ruled out in a world of rapid technological change, but this is certainly not the only plausible outcome. Chart 1 shows that, while Omnicom’s share price has fallen, analyst expectations for future free cash flow have risen. In addition, Omnicom reported 3.9% organic revenue growth in the first quarter of 2026. Its closest large peer, Publicis Groupe, reported 5.3% organic revenue growth in the first half and a positive outlook.[9]

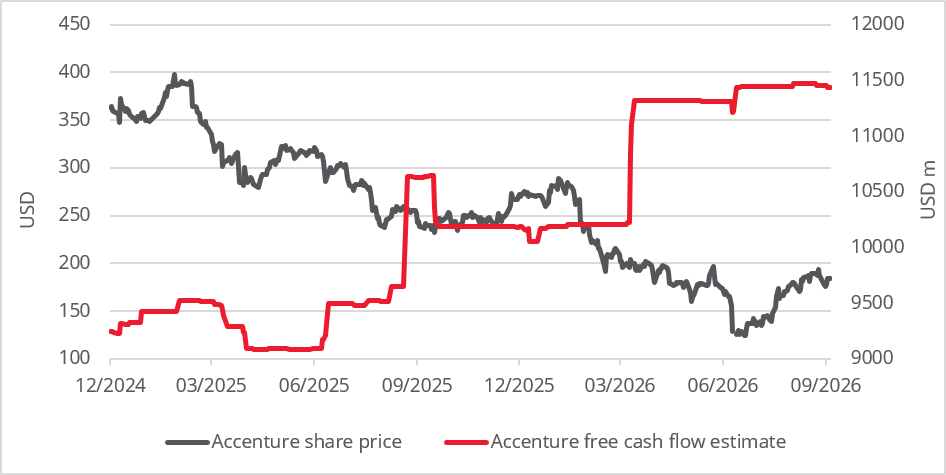
Accenture Plc., one of the leading global consultancy companies, is currently valued at approximately $116bn[10] with net debt estimated at $1bn in 12 months’ time. That valuation represents estimates for the year to August 2027 of approximately $76bn of revenue, $9bn net income and $11.5bn of free cashflow. That is around 1.5x revenue, 13x net income and a free cash flow yield of approximately 10%, while generating a dividend yield of around 3.8%[11].

Chart 2: Accenture – Share price performance since downturn vs free cash flow estimates
Source: Bloomberg, 9 September 2026. Share price, LHS. Free cash flow, RHS, shows Bloomberg point-in-time consensus estimates for forward fiscal period. The information shown above is for illustrative purposes only. Past performance is not a guide to future results.

Again, the market is basically implying that Accenture could fail within seven to eight years, yet it continues to grow. For fiscal 2026, it guided to revenue growth of 3–4% while analyst expectations for future free cash flow have increased. Accenture has also said it expects to more than double bookings from partnerships with a broad group of AI and data providers, including OpenAI, NVIDIA, Anthropic, Palantir, Databricks, Snowflake, Google Gemini and Mistral AI.[12]

These revenue growth numbers do not negate the risk that AI changes the economics of consulting, advertising or other knowledge-intensive industries. They do, however, show why we believe the market may be confusing uncertainty with certainty of failure.

Choosing the risk worth taking

All investment entails an assumption of risk. For us, the asymmetry of the risk reward is crucial. We seek to embrace a range of possible outcomes, but only where the valuation of a company’s cash flows means that the balance is skewed in our favour.

Where cash flows are durable and the share price already assumes that much can go wrong, the investment does not depend on an ideal outcome. It may simply require the business to prove more resilient than the market expects for investors to recognise that its cash flows have been undervalued.

The Strategy’s yield discipline is designed to identify such opportunities. Every holding must yield at least 25% more than the MSCI World Index at purchase. This helps us avoid paying too much for confidence and consensus, and directs us towards companies where controversy has lowered expectations.

At the portfolio level, the Strategy’s free cash flow yield is around 6%, compared with approximately 3.8% for MSCI World, while its dividend yield is around 3.2% versus 1.5% for the index. These figures are not forecasts, but they indicate that the Strategy is valued on less demanding assumptions than the market as a whole – and is being paid to wait while those assumptions are tested.

Table 1: Representative portfolio vs MSCI World index – Free cash flow and dividend yields (%)

Source: Bloomberg, Redwheel, MSCI, 31 July 2026. The information shown above is for illustrative purposes only. Past performance is not a guide to future results. *Please see the disclaimer at the end of this document for further information on the Representative Portfolio.
When uncertainty becomes opportunity

Takeovers are unusual in this Strategy because the portfolio holds large, liquid companies that are more often acquirers than targets. So, when two receive bids at substantial premiums and a third attracts bid speculation, it is a timely reminder that the gap between public-market prices and underlying corporate value can become unusually wide – and perhaps an early sign that the market is beginning to question its assumed inevitability of AI’s winners and losers.

During periods of heightened disruption, investors can crowd into apparent winners and mark down potential losers with little discrimination. We are more comfortable owning companies where the future required to justify the valuation is less heroic, free cash flows and dividends provide tangible support, and investors are paid to wait for the market’s assumptions to be tested.

Sources

[1] Redwheel, July 2026

[2] Portfolio holdings are subject to change at any time without notice. This information should not be construed as a recommendation to purchase or sell any security.

[3] The Strategy held Beazley from February 2024 to August 2026

[4] London Stock Exchange, February 2026

[5] Reuters, M&A Society, May 2026

[6] Reuters, May 2026

[7] Bloomberg, August 2026

[8] Bloomberg consensus estimates, Redwheel analysis, July 2026

[9] Source: Omnicom Group, Q2 2026 results, 28 July 2026; Publicis Groupe, H1 2026 results, 16 July 2026.

[10] Bloomberg, August 2026

[11] Bloomberg consensus estimates, Redwheel analysis, July 2026

[12] Source: Accenture, Q3 fiscal 2026 results and earnings call, 18 June 2026

Key Information

No investment strategy or risk management technique can guarantee returns or eliminate risks in any market environment. Past performance is not a guide to the future. The prices of investments and income from them may fall as well as rise and investors may not get back the full amount invested. Forecasts and estimates are based upon subjective assumptions about circumstances and events that may not yet have taken place and may never do so. The statements and opinions expressed in this article are those of the author as of the date of publication, and do not necessarily represent the view of Redwheel. This article does not constitute investment advice and the information shown is for illustrative purposes only.

*Representative Portfolio

Portfolio characteristics, top ten holdings, sector allocation, country allocation, attribution, volatility, yield, dividend and ESG information are based on a representative portfolio, which is TM Redwheel Global Equity Income Fund. Redwheel believes that precisely this account within the strategy most closely reflects the current portfolio management style for the Redwheel Global Equity Income Strategy. Portfolio holdings are subject to change without notice. The information shown is for illustrative purposes only and is not intended to be, and should not be interpreted as, recommendations or advice.
In case you missed it

Global Intrinsic Value

Despite persistent outflows, global investor underweights and little direct exposure to the AI-led market rally, UK equities have generated strong relative returns. Larry Furness, Redwheel Value & Income, examines how low valuations, share buybacks, takeover activity and the recovery in value stocks have contributed to that outcome.

16 September, 2026 | 09:35am
Convertible Bonds

Davide Basile, Lead Portfolio Manager, Redwheel Convertible Bonds, marks the first year of Redwheel’s Enhanced Index Focus Convertibles strategy. He explores the case for balanced global convertible exposure and explains how the Strategy’s three implementation levers seek to offset fees and enhance net returns.

9 September, 2026 | 03:10pm
Natural Capital

Natural capital is often framed as a narrow sustainability theme. A more useful way to think about it is that the biodiversity it supports and the ecosystem services that flow from it are part of the operating backbone of the real economy: the water, waste and environmental systems that allow cities to function, industries to expand and societies to remain productive under tightening resource and regulatory constraints. That is why the investable universe for natural capital solutions is broader, and more economically relevant, than it is often given credit for.

7 September, 2026 | 11:50am

Disclaimer

Redwheel ® and Ecofin ® are registered trademarks of RWC Partners Limited (“RWC”). The term “Redwheel” may include any one or more Redwheel branded regulated entities including RWC Asset Management LLP, which is authorised and regulated by the UK Financial Conduct Authority and the US Securities and Exchange Commission (“SEC”); RWC Asset Advisors (US) LLC, which is registered with the SEC;  RWC Singapore (Pte) Limited, which is licensed as a Licensed Fund Management Company by the Monetary Authority of Singapore; Redwheel Australia Pty Ltd is an Australian Financial Services Licensee with the Australian Securities and Investment Commission; and Redwheel Europe Fondsmæglerselskab A/S which is regulated by the Danish Financial Supervisory Authority.

Redwheel may act as investment manager or adviser, or otherwise provide services, to more than one product pursuing a similar investment strategy or focus to the product detailed in this document. Redwheel and RWC (together “Redwheel Group”) seeks to minimise any conflicts of interest, and endeavours to act at all times in accordance with its legal and regulatory obligations as well as its own policies and codes of conduct.

This document is directed only at professional, institutional, wholesale or qualified investors. The services provided by Redwheel are available only to such persons. It is not intended for distribution to and should not be relied on by any person who would qualify as a retail or individual investor in any jurisdiction or for distribution to, or use by, any person or entity in any jurisdiction where such distribution or use would be contrary to local law or regulation.

This document has been prepared for general information purposes only and has not been delivered for registration in any jurisdiction nor has its content been reviewed or approved by any regulatory authority in any jurisdiction.

The information contained herein does not constitute: (i) a binding legal agreement; (ii) legal, regulatory, tax, accounting or other advice; (iii) an offer, recommendation or solicitation to buy or sell shares in any fund, security, commodity, financial instrument or derivative linked to, or otherwise included in a portfolio managed or advised by Redwheel; or (iv) an offer to enter into any other transaction whatsoever (each a “Transaction”). Redwheel Group bears no responsibility for your investment research and/or investment decisions and you should consult your own lawyer, accountant, tax adviser or other professional adviser before entering into any Transaction. No representations and/or warranties are made that the information contained herein is either up to date and/or accurate and is not intended to be used or relied upon by any counterparty, investor or any other third party.

Redwheel Group uses information from third party vendors, such as statistical and other data, that it believes to be reliable. However, the accuracy of this data, which may be used to calculate results or otherwise compile data that finds its way over time into Redwheel Group research data stored on its systems, is not guaranteed. If such information is not accurate, some of the conclusions reached or statements made may be adversely affected. Any opinion expressed herein, which may be subjective in nature, may not be shared by all directors, officers, employees, or representatives of Group and may be subject to change without notice. Redwheel Group is not liable for any decisions made or actions or inactions taken by you or others based on the contents of this document and neither Redwheel Group nor any of its directors, officers, employees, or representatives (including affiliates) accepts any liability whatsoever for any errors and/or omissions or for any direct, indirect, special, incidental, or consequential loss, damages, or expenses of any kind howsoever arising from the use of, or reliance on, any information contained herein.

Information contained in this document should not be viewed as indicative of future results. Past performance of any Transaction is not indicative of future results. The value of investments can go down as well as up. Certain assumptions and forward looking statements may have been made either for modelling purposes, to simplify the presentation and/or calculation of any projections or estimates contained herein and Redwheel Group does not represent that that any such assumptions or statements will reflect actual future events or that all assumptions have been considered or stated. There can be no assurance that estimated returns or projections will be realised or that actual returns or performance results will not materially differ from those estimated herein. Some of the information contained in this document may be aggregated data of Transactions executed by Redwheel that has been compiled so as not to identify the underlying Transactions of any particular customer.

No representations or warranties of any kind are intended or should be inferred with respect to the economic return from, or the tax consequences of, an investment in a Redwheel-managed fund.

This document expresses no views as to the suitability or appropriateness of the fund or any other investments described herein to the individual circumstances of any recipient.

The information transmitted is intended only for the person or entity to which it has been given and may contain confidential and/or privileged material. In accepting receipt of the information transmitted you agree that you and/or your affiliates, partners, directors, officers and employees, as applicable, will keep all information strictly confidential. Any review, retransmission, dissemination or other use of, or taking of any action in reliance upon, this information is prohibited. Any distribution or reproduction of this document is not authorised and is prohibited without the express written consent of Redwheel Group.

Funds managed by Redwheel are not, and will not be, registered under the Securities Act of 1933 (the “Securities Act”) and are not available for purchase by US persons (as defined in Regulation S under the Securities Act) except to persons who are “qualified purchasers” (as defined in the Investment Company Act of 1940) and “accredited investors” (as defined in Rule 501(a) under the Securities Act).

This document does not constitute an offer to sell, purchase, subscribe for or otherwise invest in units or shares of any fund managed by Redwheel. Any offering is made only pursuant to the relevant offering document and the relevant subscription application. Prospective investors should review the offering memorandum in its entirety, including the risk factors in the offering memorandum, before making a decision to invest.

AIFMD and Distribution in the European Economic Area (“EEA”)

The Alternative Fund Managers Directive (Directive 2011/61/EU) (“AIFMD”) is a regulatory regime which came into full effect in the EEA on 22 July 2014. RWC Asset Management LLP is an Alternative Investment Fund Manager (an “AIFM”) to certain funds managed by it (each an “AIF”). The AIFM is required to make available to investors certain prescribed information prior to their investment in an AIF. The majority of the prescribed information is contained in the latest Offering Document of the AIF. The remainder of the prescribed information is contained in the relevant AIF’s annual report and accounts. All of the information is provided in accordance with the AIFMD.

In relation to each member state of the EEA (each a “Member State”), this document may only be distributed and shares in a Redwheel fund (“Shares”) may only be offered and placed to the extent that (a) the relevant Redwheel fund is permitted to be marketed to professional investors in accordance with the AIFMD (as implemented into the local law/regulation of the relevant Member State); or (b) this document may otherwise be lawfully distributed and the Shares may lawfully be offered or placed in that Member State (including at the initiative of the investor).

Information Required for Offering in Switzerland of Foreign Collective Investment Schemes to Qualified Investors within the meaning of Article 10 CISA.

This is an advertising document.

The representative and paying agent of the Redwheel-managed funds in Switzerland (the “Representative in Switzerland”) FIRST INDEPENDENT FUND SERVICES LTD, Feldeggstrasse 12, CH-8008 Zurich. Swiss Paying Agent: Helvetische Bank AG, Seefeldstrasse 215, CH-8008 Zurich. In respect of the units of the Redwheel-managed funds offered in Switzerland, the place of performance is at the registered office of the Swiss Representative. The place of jurisdiction is at the registered office of the Swiss Representative or at the registered office or place of residence of the investor.

No investment strategy or risk management technique can guarantee returns or eliminate risks in any market environment.The term “RWC” may include any one or more RWC branded entities including RWC Partners Limited and RWC Asset Management LLP, each of which is authorised and regulated by the UK Financial Conduct Authority and, in the case of RWC Asset Management LLP, the US Securities and Exchange Commission; RWC Asset Advisors (US) LLC, which is registered with the US Securities and Exchange Commission; and RWC Singapore (Pte) Limited, which is licensed as a Licensed Fund Management Company by the Monetary Authority of Singapore.RWC may act as investment manager or adviser, or otherwise provide services, to more than one product pursuing a similar investment strategy or focus to the product detailed in this audio. RWC seeks to minimise any conflicts of interest, and endeavours to act at all times in accordance with its legal and regulatory obligations as well as its own policies and codes of conduct.This audio is directed only at professional, institutional, wholesale or qualified investors. The services provided by RWC are available only to such persons. It is not intended for distribution to and should not be relied on by any person who would qualify as a retail or individual investor in any jurisdiction or for distribution to, or use by, any person or entity in any jurisdiction where such distribution or use would be contrary to local law or regulation.This audio has been prepared for general information purposes only and has not been delivered for registration in any jurisdiction nor has its content been reviewed or approved by any regulatory authority in any jurisdiction. The information contained herein does not constitute: (i) a binding legal agreement; (ii) legal, regulatory, tax, accounting or other advice; (iii) an offer, recommendation or solicitation to buy or sell shares in any fund, security, commodity, financial instrument or derivative linked to, or otherwise included in a portfolio managed or advised by RWC; or(iv) an offer to enter into any other transaction whatsoever (each a “Transaction”). No representations and/or warranties are made that the information contained herein is either up to date and/or accurate and is not intended to be used or relied upon by any counterparty, investor or any other third party.RWC uses information from third party vendors, such as statistical and other data, that it believes to be reliable. However, the accuracy of this data, which may be used to calculate results or otherwise compile data that finds its way over time into RWC research data stored on its systems, is not guaranteed. If such information is not accurate, some of the conclusions reached or statements made may be adversely affected. RWC bears no responsibility for your investment research and/or investment decisions and you should consult your own lawyer, accountant, tax adviser or other professional adviser before entering into any Transaction. Any opinion expressed herein, which may be subjective in nature, may not be shared by all directors, officers, employees, or representatives of RWC and may be subject to change without notice. RWC is not liable for any decisions made or actions or in actions taken by you or others based on the contents of this audio and neither RWC nor any of its directors, officers, employees, or representatives (including affiliates) accepts any liability whatsoever for any errors and/or omissions or for any direct, indirect, special, incidental, or consequential loss, damages, or expenses of any kind howsoever arising from the use of, or reliance on, any information contained herein.Information contained in this audio should not be viewed as indicative of future results. Past performance of any Transaction is not indicative of future results. The value of investments can go down as well as up. Certain assumptions and forward looking statements may have been made either for modelling purposes, to simplify the audio and/or calculation of any projections or estimates contained herein and RWC does not represent that that any such assumptions or statements will reflect actual future events or that all assumptions have been considered or stated. Forward-looking statements are inherently uncertain, and changing factors such as those affecting the markets generally, or those affecting particular industries or issuers, may cause results to differ from those discussed. Accordingly, there can be no assurance that estimated returns or projections will be realised or that actual returns or performance results will not materially differ from those estimated herein. Some of the information contained in this audio may be aggregated data of Transactions executed by RWC that has been compiled so as not to identify the underlying Transactions of any particular customer.The information transmitted is intended only for the person or entity to which it has been given and may contain confidential and/or privileged material. In accepting receipt of the information transmitted you agree that you and/or your affiliates, partners, directors, officers and employees, as applicable, will keep all information strictly confidential. Any review, retransmission, dissemination or other use of, or taking of any action in reliance upon, this information is prohibited. The information contained herein is confidential and is intended for the exclusive use of the intended recipient(s) to which this audio has been provided. Any distribution or reproduction of this audio is not authorised and is prohibited without the express written consent of RWC or any of its affiliates.Changes in rates of exchange may cause the value of such investments to fluctuate. An investor may not be able to get back the amount invested and the loss on realisation may be very high and could result in a substantial or complete loss of the investment. In addition, an investor who realises their investment in a RWC-managed fund after a short period may not realise the amount originally invested as a result of charges made on the issue and/or redemption of such investment. The value of such interests for the purposes of purchases may differ from their value for the purpose of redemptions. No representations or warranties of any kind are intended or should be inferred with respect to the economic return from, or the tax consequences of, an investment in a RWC-managed fund. Current tax levels and reliefs may change. Depending on individual circumstances, this may affect investment returns. Nothing in this document constitutes advice on the merits of buying or selling a particular investment. This audio expresses no views as to the suitability or appropriateness of the fund or any other investments described herein to the individual circumstances of any recipient.AIFMD and Distribution in the European Economic Area (“EEA”)The Alternative Fund Managers Directive (Directive 2011/61/EU)(“AIFMD”) is a regulatory regime which came into full effect in the EEA on 22 July 2014. RWC Asset Management LLP is an Alternative Investment Fund Manager (an “AIFM”) to certain funds managed by it (each an “AIF”). The AIFM is required to make available to investors certain prescribed information prior to their investment in an AIF. The majority of the prescribed information is contained in the latest Offering Document of the AIF. The remainder of the prescribed information is contained in the relevant AIF’s annual report and accounts. All of the information is provided in accordance with the AIFMD.In relation to each member state of the EEA (each a “Member State”),this document may only be distributed and shares in a RWC fund(“Shares”) may only be offered and placed to the extent that (a) the relevant RWC fund is permitted to be marketed to professional investors in accordance with the AIFMD (as implemented into the local law/regulation of the relevant Member State); or (b) this audio may otherwise be lawfully distributed and the Shares may lawfully offered or placed in that Member State (including at the initiative of the investor).Information Required for Distribution of Foreign Collective Investment Schemes to Qualified Investors in SwitzerlandThe representative and paying agent of the RWC-managed funds in Switzerland (the “Representative in Switzerland”) FIRST INDEPENDENT FUND SERVICES LTD, Klausstrasse 33, CH-8008 Zurich. Swiss Paying Agent: Helvetische Bank AG, Seefeldstrasse 215, CH-8008 Zurich. In respect of the units of the RWC-managed funds distributed in Switzerland, the place of performance and jurisdiction is at the registered office of the Representative in Switzerland.